
Deal Volume in the Packaging Industry
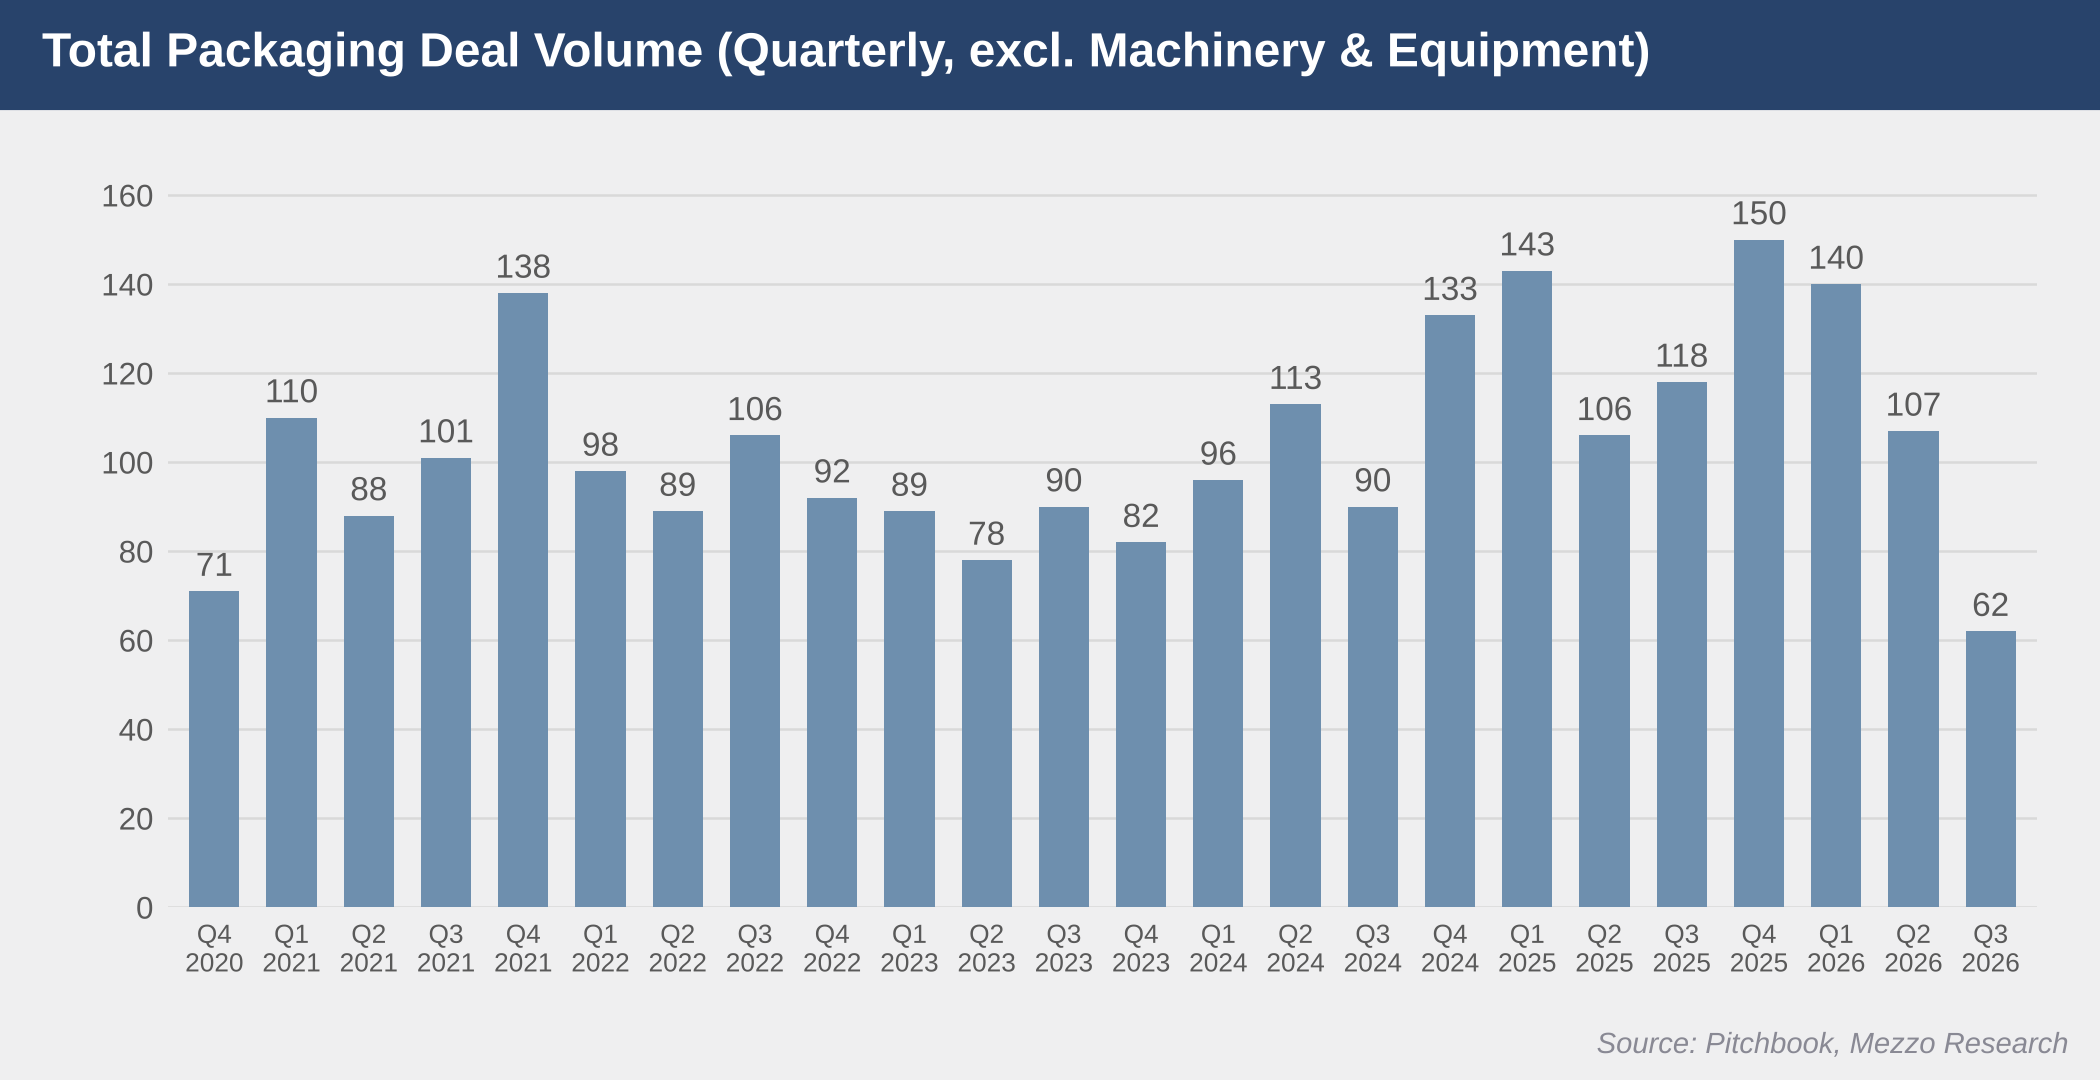
Packaging transactions are on pace to decrease in volume by 20% in 2026, with the Trailing 4 Quarters ("T4Q") ending September 30) falling 8%. Quarterly volumes have declined sequentially since Q4 of 2025, with Q3-2026's 62 transactions the lowest logged volume since Q3 of 2020. Closings are a "lagging indicator" as processes take six+ months to complete; as such, we anticipate further slow quarters as we head into 2027.
The culprits for the decrease were many: trade policy, war and input price disruption, higher inflation, and increased interest rates – all of which increased uncertainty for the global economy. Facing these challenges, "big ticket" purchases, whether they be new production lines or, in our case, acquisitions, became viewed as too risky.
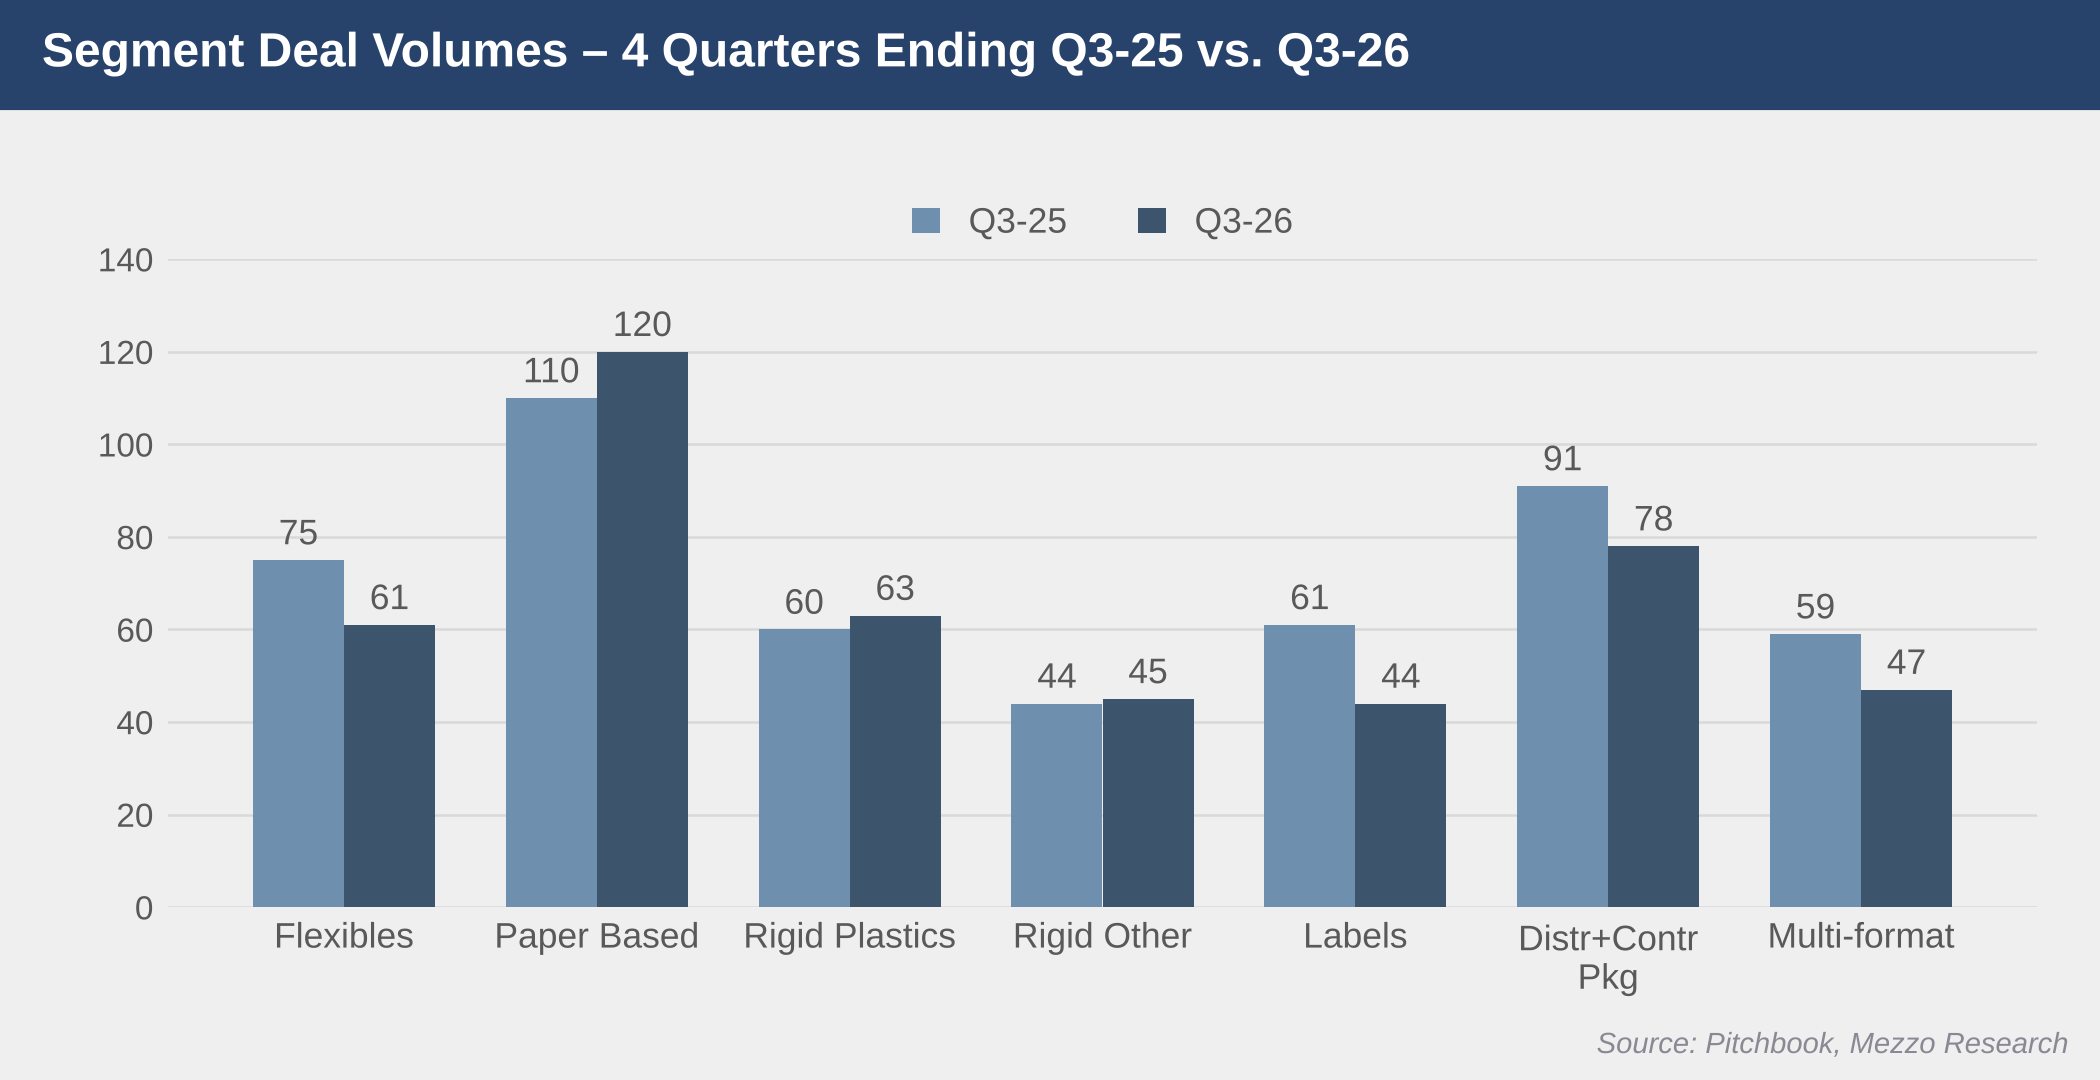
The trailing four quarters saw deal volume declines across most segments, with only Paper showing a meaningful increase over the four quarters ending September 2025.
Want more insights into the Packaging Industry?
Looking to explore strategic options in the Packaging sector?
Connect with Stuart Sanford, Director at Mezzo. Whether you're considering a sale, acquisition, or capital raise, Stuart brings deep industry knowledge and transaction expertise to help you evaluate your next move with confidence.