
Pricing in the Packaging Industry
At first blush, overall pricing appears to be holding steady+ in 2026, with EBITDA multiples roughly steady. As discussed below, however, underlying data points to weakness among major packaging segments. The overall EBITDA multiple of 8.6x is in line with the longer-term average of ~8.5x, and our view is that these prices should be expected to remain in this range for the near term. One noted caveat to this is that if interest rates continue to climb, there will need to be an adjustment in either pricing for acquisitions or the expected return on LBOs.
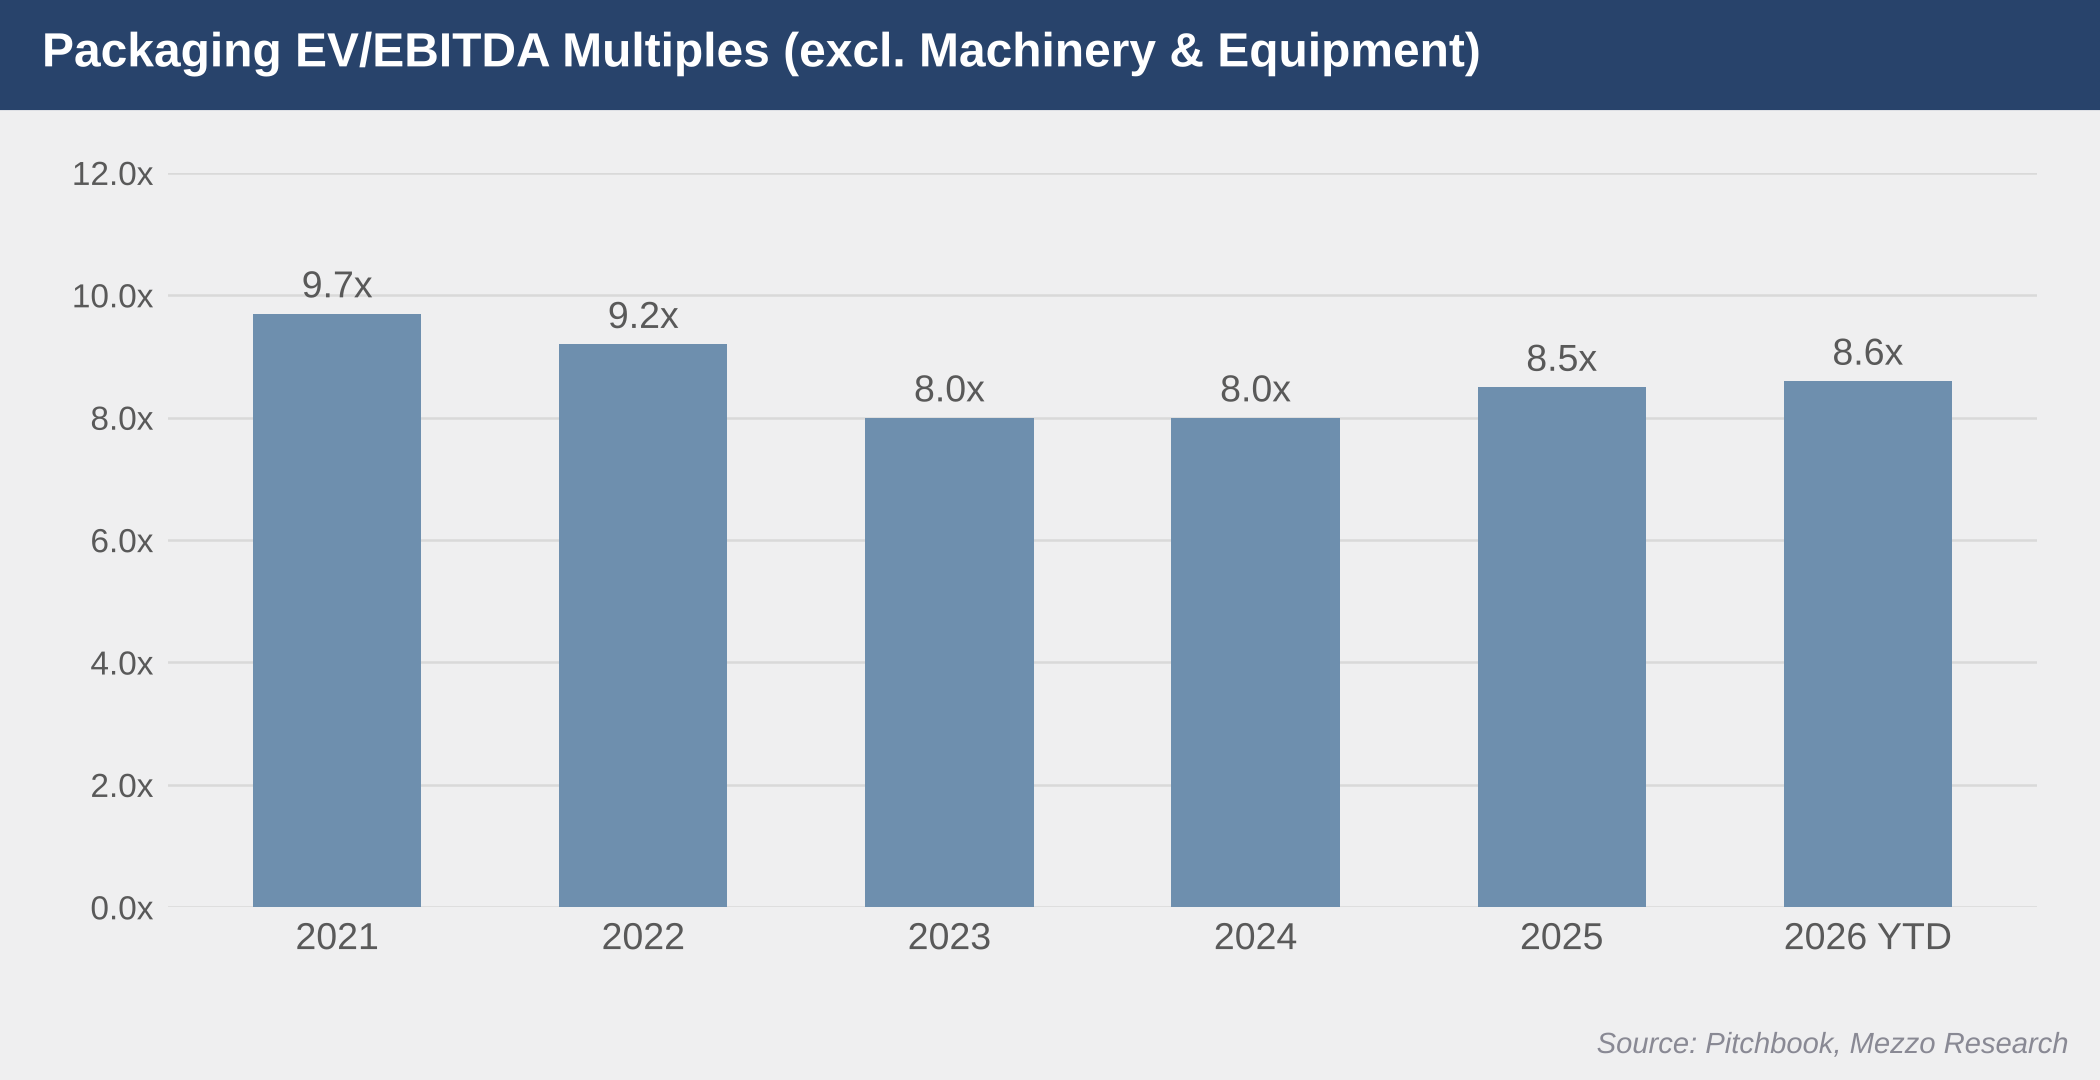
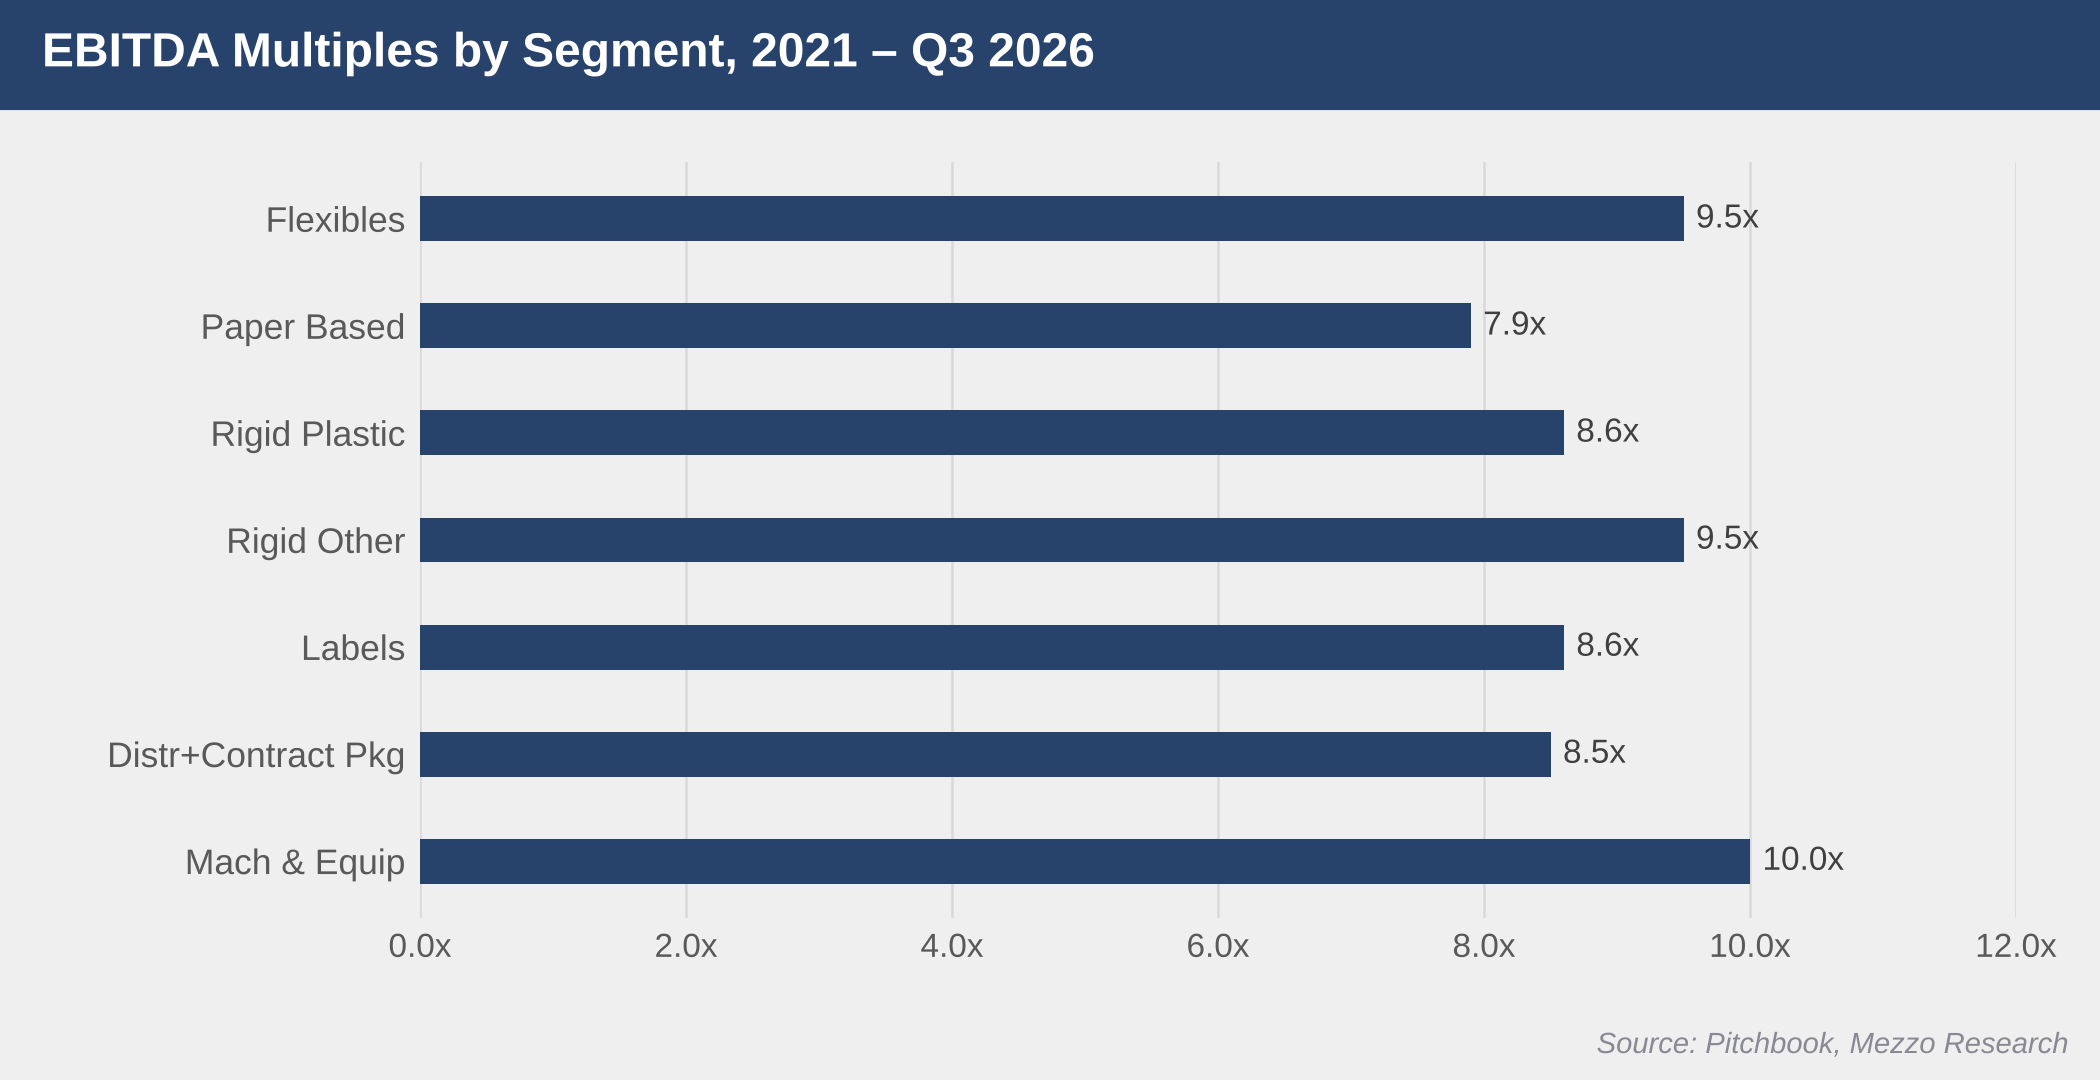
Over the longer-term view, pricing among packaging segments trades in a band of 7x to 10x of EBITDA. Recent trends indicate caution, as the most recent 2025-YTD 2026 period has seen a nearly 1.0x reduction in EBITDA multiples among Flexibles, Rigid Plastic, Paper-based, Labels, and Rigid Other (Glass, Metal, Wood). Only Distribution + Contract Packaging, Machinery & Equipment, and Multi-format Packaging have enjoyed consistent pricing in year-to-date 2026.
Want more insights into the Packaging Industry?
Looking to explore strategic options in the Packaging sector?
Connect with Stuart Sanford, Director at Mezzo. Whether you're considering a sale, acquisition, or capital raise, Stuart brings deep industry knowledge and transaction expertise to help you evaluate your next move with confidence.